- Due-diligence guides
- Flood insurance
Free tool · No signup
Flood insurance due diligence, before you write the offer.
The FEMA zone, the floodway and whether insurance is required, in about 20 seconds. Free for the live check; $99 for the full report.
Official FEMA National Flood Hazard Layer · No card needed
The number you came for
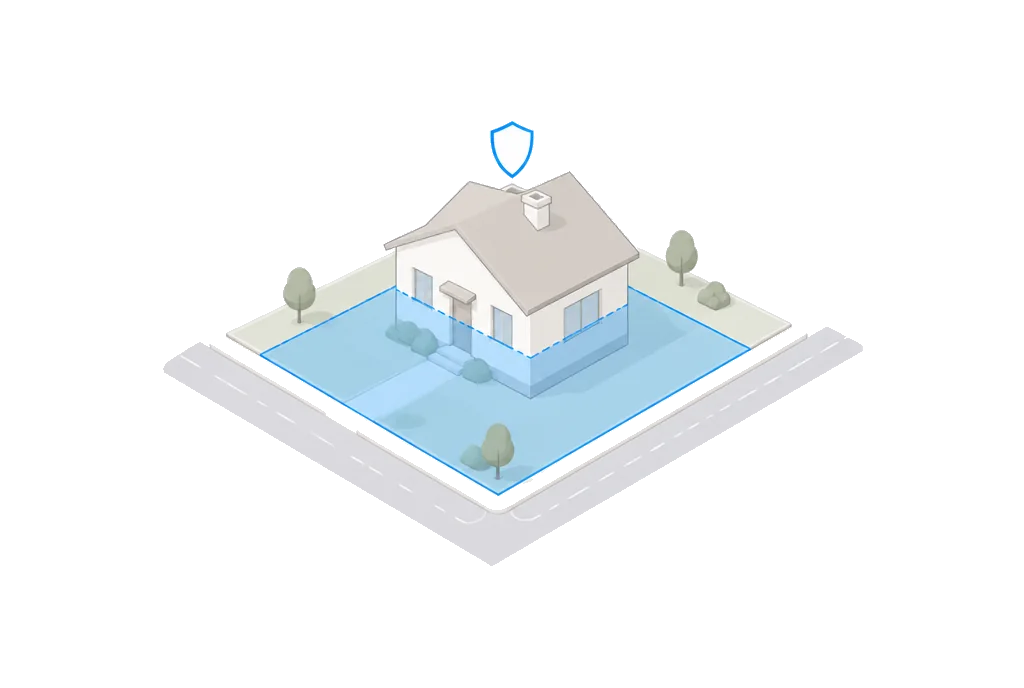
Flood insurance, by zone: what is required.
Under Risk Rating 2.0, FEMA prices each building on its own flood risk, so the zone tells you whether insurance is required and only a quote tells you what it costs. Get the quote before the LOI.
| Zone | What it means | Required? |
|---|---|---|
| Zone X | Minimal risk (outside 100-yr floodplain) | Not required |
| Zone B / C | Moderate risk (500-yr floodplain, shaded X) | Not required |
| Zone A | 100-yr floodplain, no BFE published | Required with federally-backed mortgage |
| Zone AE | 100-yr floodplain with base flood elevation | Required with federally-backed mortgage |
| Zone VE | Coastal high-hazard (wave action expected) | Required, with strict construction standards |
Why check before LOI
A VE-zone parcel can carry more insurance than property tax.
If a VE policy quotes at $12,000 a year on a $400,000 land buy, that is 3% of the price every year, and $120,000 of pre-tax carry over a 10-year hold. Getting the zone and a quote before the LOI moves that number into your offer instead of your surprise column.
- The zone determines the requirement. X and shaded-X: insurance is optional. A, AE, V, VE: insurance is mandatory with any federally-backed mortgage, and lenders will not close without a policy in force.
- The BFE determines the build cost. In Zone AE, the lowest floor of any new construction has to sit above the base flood elevation. Elevation costs typically add $10,000–$80,000 to the vertical, before insurance savings kick in.
- A LOMA can drop the requirement. A structure a licensed surveyor certifies above the BFE can be removed from the SFHA by a Letter of Map Amendment, and the mandatory-purchase requirement goes with it. Buildability does not screen for LOMA eligibility; the surveyor’s elevation certificate is the check.
- Zone X does not mean zero risk. Properties FEMA rates “minimal risk” still flood. Serious buyers verify regardless of what the seller volunteered.
How to check
Two moves, both cheaper than the risk.
A free live check tells you whether flood is a factor. A full report gives you a defensible record with the BFE, the floodway and every other diligence factor in one file.
Live flood zone check
Free- FEMA flood zone designation (X, A, AE, V, VE)
- Special Flood Hazard Area (SFHA) status
- No signup, no card
Full property report
$99- FEMA flood zone + base flood elevation (BFE) where published
- Floodway on the point and on the lot, and the share of the lot inside an SFHA
- Every other Buildability factor: zoning, seismic, wildfire, soil, radon, utilities
- Free re-runs, and change alerts once it is saved to a free account
Property Reports slide from $99 to $79 at volume. No record, no charge.
What land buyers actually ask about flood.
How do I check flood insurance requirements before buying land?
The fastest path is a FEMA flood zone lookup by address: free, live, and about 20 seconds. If the parcel returns Zone A, AE, V, or VE, insurance is mandatory with a federally-backed mortgage; a quote from a FEMA-listed agent gives the cost. The zone check alone is enough to know whether flood belongs in the LOI.
What does it cost to verify flood status before buying?
Nothing, for a live zone check. Buildability’s flood-zone tool is free and uses official FEMA National Flood Hazard Layer (NFHL) data. If you want a defensible written record for your file, with the base flood elevation, the floodway and every other factor a lender or committee will ask about, a full Buildability report is $99 (sliding to $79 at volume) and includes the flood work alongside zoning, seismic, wildfire, and soil.
How much does flood insurance cost per zone?
The zone does not set the price. Under Risk Rating 2.0, FEMA prices each building on its own flood risk, so two houses in the same zone can quote very differently. The zone still decides whether a federally-backed mortgage requires a policy; get a quote from your agent before the LOI.
Can flood insurance kill an otherwise good deal?
Yes. If a VE-zone policy quotes at $12,000 a year on a $400,000 land buy, that is 3% of the purchase price every year, and $120,000 of pre-tax carry over a 10-year hold. Getting the zone and a quote before the LOI moves that number into your offer, not your surprise column.
What is a LOMA and can it help me?
A Letter of Map Amendment (LOMA) is FEMA’s process for removing a specific structure or parcel from a Special Flood Hazard Area when a licensed surveyor certifies it is above the base flood elevation. Cost: $500–$5,000. Timeline: 60–90 days.
How accurate is FEMA flood zone data?
FEMA maps are the legal standard for insurance and lending decisions, but they are periodically revised as development and better topographic data change the picture. Buildability reads the National Flood Hazard Layer when the report runs and dates the read, so you can point to the exact vintage in your file.
When during the buying process should I check flood status?
Twice. First, before you write the LOI: a free zone check tells you whether flood insurance is a factor at all. Second, before closing: a full report records the zone designation, the BFE and the floodway on the lot, dated. Doing it once, late, is how buyers get surprised at underwriting.
Does Buildability work in my area?
FEMA’s National Flood Hazard Layer covers most of the country; where a county has no digital map, the report says the zone is unmapped rather than guessing.
Due-diligence guide series · 4 guides
More in the series.
Radon cost vs. property value
EPA Zones and mitigation cost for investors buying in high-radon counties.
Read the guideLot subdivision rules by state
Statewide pre-emption (CA/OR/WA) versus local zoning, plus the cost and timeline of a split.
Read the guideLiquefaction risk & soil analysis
USGS ground motion, USDA soils, and the foundation-strategy price ranges.
Read the guide
Verify before you sign.
The zone check takes about a minute. The surprise on your first premium quote takes a month to unwind.
Free live check · No card needed · Official FEMA NFHL data